Upgrade - Boost Money

Screenshots
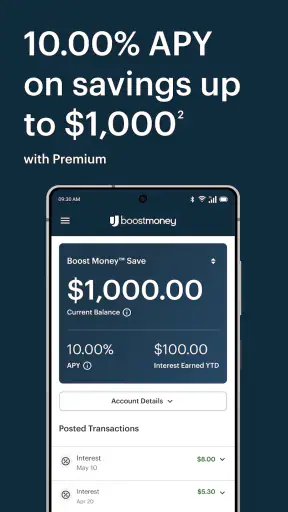
Details
- Rating
- 50.00 reviews
- Version
- 1.3.0
- Developer
- Upgrade, Inc.
Analysis by Norviv
I approached Upgrade - Boost Money as a practical finance app rather than something to open only when I need a quick account snapshot. Its promise is easy to understand: bring spending, saving, and credit-building into one place. In everyday use, that combination matters because these activities are connected, but they are not the same task. A payment decision affects the money left for saving, while a credit-building goal requires more patience and consistency than a simple budget check.
That makes this app most interesting for someone who wants a single starting point for managing those priorities. It is a free finance app from Upgrade, Inc., available to users aged Everyone, and its current version is 1.3.0. The app has reached over 50 thousand installs and holds a 4.1 average from around 172 ratings, which suggests a generally positive reception without making it look universally perfect. I would treat it as a useful financial companion, not as a replacement for careful decisions or a complete financial plan.
From an unstructured money routine to a clearer workflow
I found that the most useful way to think about this section is as a shift from reacting to balances toward following a repeatable sequence: check what is committed, decide what is flexible, then choose the next action. That distinction matters because a clearer workflow should make decisions easier without pretending to make them for me. From there, I can judge whether the routine remains practical when the month gets busy.
Starting with the problem you actually have
The best way to use this app is to begin with a specific money problem. Maybe your monthly spending feels scattered, your savings habit keeps stopping, or you want to become more deliberate about building credit. Opening a finance app without deciding what you want to improve can turn into passive checking: you look at balances, feel informed for a minute, and then return to the same habits.
With Upgrade - Boost Money, I would start by choosing one immediate outcome. If spending is the issue, the first job is to understand where money is going. If saving is the issue, the important question is not simply how much is available today, but what amount can be set aside without creating a shortfall later. If credit is the priority, the workflow needs a longer view and more discipline than a one-time transfer.
This is one of the app’s practical strengths. Its three-part focus encourages me to connect daily choices with broader financial progress. The trade-off is that the same broad scope can feel less focused than an app built only for detailed budgeting or only for savings. Users who want deep category customization may prefer a specialist tool, while users who want a central place to begin may find the wider approach more comfortable.
Setting up the first useful routine
I would not try to change every part of my finances at once. A better first session would be about creating a repeatable check-in. I would review current spending, identify the bills and purchases that must be protected, and then decide what amount can reasonably move toward saving. Only after that would I consider how credit-building fits into the rest of the month.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
This order matters because saving money that is needed for an upcoming payment is not real progress. The app can support a more organized approach, but it cannot know the personal importance of every expense simply by showing financial information. I still need to apply judgment. The useful handoff is from the app’s overview to my own decision-making: it helps me see the situation, but I remain responsible for choosing a safe amount.
A small routine is more realistic than an ambitious financial reset. I would check the app after an ordinary spending period, not only after a particularly good week. That makes it easier to spot recurring pressure, such as frequent small purchases that feel harmless individually but make saving difficult when combined. This kind of pattern recognition is more valuable than chasing a perfect balance on a single day.
Following the flow from spending to saving
The spending side should be treated as the input stage. Before I make a saving decision, I want to know what money has already been committed and what remains flexible. The app’s combined positioning is helpful here because it keeps spending and saving in the same financial conversation instead of forcing me to jump between unrelated tools.
In a realistic example, I might check the app after receiving income and separate three mental buckets: essential commitments, ordinary day-to-day spending, and a possible saving amount. The point is not to create an elaborate spreadsheet inside the app. The point is to make the next decision with fewer surprises. If the spending picture is tighter than expected, the right result may be a smaller saving move rather than an unrealistic target that has to be reversed later.
A non-obvious benefit of this workflow is that it encourages me to inspect timing, not just totals. A monthly total can look manageable while the timing of several payments creates a difficult week. I would use the app as a checkpoint before moving money, especially when a large recurring obligation is approaching. That habit can prevent the common mistake of treating the current balance as entirely available.
The limitation is equally important: a combined finance experience can simplify the overview while leaving the user to do some interpretation. Someone who wants highly granular envelope budgeting, extensive manual tagging, or a detailed forecasting system may find a dedicated budgeting app more suitable. Upgrade - Boost Money makes more sense for a person who values a connected overview over a very specialized planning workspace.
Turning a saving intention into a decision
Saving is where many finance apps sound more motivating than they are practical. I prefer to think of the app as a place to support a decision I have already made, rather than as a machine that will automatically fix inconsistent habits. The useful question is: what amount can I move or preserve while still handling ordinary life?
For a short-term goal, I would define the purpose before acting. An emergency cushion, a planned purchase, and a buffer for irregular bills all require different levels of access and patience. Keeping that purpose visible helps prevent me from treating every saved amount as spare money. The app’s value is strongest when it helps connect the action to the wider picture of spending and credit, rather than when I use it as a simple number display.
I would also review the result after a normal month, including the weeks when plans go wrong. If a saving target repeatedly forces me to undo the decision, the target is too aggressive or the spending plan needs attention. That is a useful insight because a failed saving attempt is not automatically a failure of the app. It may reveal that the original plan did not match real cash flow.
There is a handoff here that users should understand clearly. The app can organize the financial step, but the user must supply realistic priorities and follow through. If you want an entirely automatic experience that makes every decision for you, this will not remove the need for attention. If you want a place to make those decisions with spending and credit in view, it has a more convincing role.
Bringing credit-building into the same routine
Credit-building is the part that requires the most patience. It is easy to expect a visible result after a few actions, but responsible credit habits are about consistency and understanding obligations. I would therefore use this area as a long-term checkpoint, not something to monitor anxiously every day.
The practical workflow is to keep credit goals connected to affordability. A credit-related action should never encourage spending beyond what can be handled comfortably. I would first make sure ordinary expenses and saving plans are stable, then consider whether the credit-building path fits my situation. This order protects the more important principle: improving a financial profile should not create avoidable financial stress.
That is also where I would be most cautious about recommendations. A person new to credit may appreciate having the subject placed beside spending and saving, because it makes the connection easier to understand. Someone already managing several credit products may want more specialized tools and more detailed control. In that case, this app could still be useful as a general overview, but I would not make it the only source of financial information.
The strongest insight here is that credit-building should be treated as a behavior workflow, not a score-chasing exercise. I would use the app to reinforce regular review, affordability, and awareness of how daily money choices affect longer-term goals. That mindset is more durable than checking for an immediate change and reacting emotionally to it.
Managing the handoffs between app and real life
The app is only one part of the process. A typical handoff begins when I notice a financial detail in the app, continues when I compare it with my actual obligations, and ends when I decide whether to spend, save, or hold money back. Each transition is a possible source of friction.
For example, the app may make a saving amount look reasonable at a glance, but I still need to remember annual expenses, upcoming travel, household changes, or an irregular bill. A clean digital view cannot automatically replace personal context. I would keep a short note of unusual commitments outside the app so that my next review is based on the whole month rather than only the most visible information.
Another handoff occurs when more than one person is involved in the household. If money decisions are shared, one person’s view of spending may not be enough to explain the final result. I would use the app to support a conversation, not assume that a single screen settles every household decision. This is a subtle but important distinction for couples, families, or anyone managing money with another person.
Notifications and frequent checking can also become counterproductive if they create anxiety. I prefer a planned review rhythm: check when there is a meaningful decision to make, then act or record the next step. The app is more useful when it changes behavior than when it simply increases the number of times I look at a balance.
What the completed workflow looks like
A successful cycle with Upgrade - Boost Money would look something like this: I begin by reviewing spending, protect essential commitments, choose a realistic saving action, and then consider the credit implications of maintaining responsible habits. After the action, I return later to compare the result with what I expected. That final comparison is important because it turns the app from a passive dashboard into part of a learning loop.
In an everyday scenario, imagine that I am paid near the start of the month and want to avoid reaching the final week with no flexibility. I would use the spending view to identify what is already spoken for, reserve room for ordinary purchases, and choose a modest saving step. I would then leave the credit-building goal in the background as a consistency objective rather than allowing it to compete with immediate bills. Mid-month, I would review whether the plan still reflects reality. If spending is higher, I would adjust early instead of waiting for a crisis.
The outcome is not necessarily a dramatic financial transformation. A more realistic result is better awareness, fewer impulsive transfers, and a clearer connection between today’s spending and tomorrow’s goals. That is a worthwhile result for a free app, especially for someone who currently manages money through scattered notes, memory, and several disconnected screens.
Its audience is therefore fairly clear to me. It suits people who want an accessible entry point into spending, saving, and credit management, particularly those who prefer one connected experience. It may also help someone who has started a financial routine but keeps losing the thread between short-term cash flow and longer-term progress.
I would be less likely to recommend it as the only tool for a professional trader, a user who needs complex household accounting, or someone who wants extensive customization and forecasting. Those people may be better served by specialized finance software. Likewise, anyone looking for a completely hands-off solution should understand that the app still depends on personal review and responsible choices.
Where the flow breaks down
The first weak point is focus. Combining several financial goals is convenient, but it can also make the experience feel broad. A user arriving with one urgent need may have to decide which part of the app deserves attention first. I would solve that by choosing one primary goal for the first few weeks and treating the other areas as supporting context.
The second weak point is interpretation. Seeing financial information is not the same as understanding what action is safe. A balance can be misleading if upcoming obligations are not considered, and a saving goal can be harmful if it leaves no room for ordinary surprises. The app can make the information easier to approach, but it cannot remove the need for financial judgment.
The third is patience. Credit-building does not fit the instant-feedback expectations created by many mobile apps. If you need immediate results, you may become frustrated or make poor decisions. I would recommend using the credit section as a steady habit tracker in your own routine, while keeping expectations realistic.
There is also a practical comparison with usual alternatives. A traditional bank app may be better for checking one institution’s transactions or completing a specific banking task. A dedicated budgeting app may win for detailed categories and manual planning. A savings-focused service may offer a more concentrated experience for one goal. Upgrade - Boost Money’s advantage is the handoff between these concerns: it gives me a single place to think about how spending affects saving and how both relate to credit. Its disadvantage is that this convenience may not satisfy users who want expert-level depth in one narrow area.
Because the app is free, the barrier to trying it is low, but that does not mean every user should adopt it permanently. I would give it a fair trial through a complete spending-and-saving cycle rather than judging it after one opening. During that period, I would ask whether it helps me make decisions sooner, understand trade-offs more clearly, and maintain a routine without adding confusion. If the answer is no, a more focused alternative is likely the better choice.
My final take after using it as a routine
Upgrade - Boost Money works best when I treat it as a guided financial checkpoint. It starts with the reality of everyday spending, passes through a saving decision, and keeps credit-building visible without making it the only objective. That workflow feels more useful than a simple promise to “manage money,” because it reflects how these choices actually interact.
I like the app for its approachable scope and its ability to put several important money questions beside one another. I also appreciate that it can suit a beginner who wants a clearer starting routine without paying for access. At the same time, I would not confuse a connected overview with complete financial planning. The user still has to check timing, protect essential commitments, and understand the consequences of each action.
My recommendation is straightforward: try it if you want one free finance app to help organize spending, saving, and credit-building in the same workflow. Skip it if you already rely on a detailed specialist system or need advanced control that a broad mobile experience is unlikely to provide. For the right user, the real strength is turning scattered money decisions into one repeatable process. That is a modest goal, but in daily finances, a process you can actually maintain is often more valuable than a complicated plan you abandon.
With its Everyone age rating, free access, and development by Upgrade, Inc., the app is easy to consider as a low-risk starting point for a more deliberate money routine. Its 4.1 average and over 50 thousand installs show that it has found an audience, while the experience itself gives me a more useful conclusion: it is not a magic financial fix, but it can become a practical bridge between what I spend today, what I save next, and the credit habits I want to build over time.
Frequently Asked Questions
01What is Upgrade - Boost Money, and how does it work?
Upgrade - Boost Money is a personal finance app designed to help users manage borrowing, spending, and everyday money decisions in one place. Depending on eligibility, it may provide access to personal loan offers, credit-related tools, educational resources, and account management features. Available products, rates, limits, and terms can vary by applicant, location, credit profile, and applicable regulations.
02Can I apply for a loan through Upgrade - Boost Money?
The app may allow eligible users to check personal loan options and submit an application digitally. Checking available offers may involve providing personal, employment, income, and financial information, while the final application can require additional verification. Approval is not guaranteed, and accepting a loan may result in interest, origination fees, repayment obligations, and possible effects on your credit profile.
03Will using Upgrade - Boost Money affect my credit score?
The effect on your credit depends on the feature you use and the stage of the application. Some eligibility checks may use a soft credit inquiry that does not affect your score, while submitting a formal application can result in a hard inquiry. If you receive credit, missed or late payments may be reported and could negatively affect your credit history.
04Is Upgrade - Boost Money safe to use?
Upgrade - Boost Money may use standard security measures such as account authentication, encryption, and identity verification to help protect user information. However, no online financial service is completely risk-free. Download the app only from an official app store, review its privacy policy and permissions, enable strong account security, and avoid sharing passwords or verification codes with anyone.
05What should I check before downloading and using the app?
Before downloading, confirm that the app is available in your country and that your device meets its operating requirements. Review the provider’s fees, interest rates, repayment terms, privacy practices, and eligibility rules rather than relying only on promotional information. You should also compare any offered credit with alternatives and borrow only an amount you can comfortably repay.


